Crypto
Crypto Correlation & Pairs: Which Coins Move Together, and Which Drifted Apart
10 min read · Updated 9 Nov 2026
Pair trading asks a simple question about two things that usually move together: is today's gap between them a lasting change, or a stretch that tends to close? On NSE the natural pairs are two companies in the same business. On crypto, almost every coin moves with Bitcoin, so almost every pair is correlated, and reading the page well means knowing what that does to the numbers.
The Correlation & Pairs page tests the liquid USDT pairs against each other, keeps the ones that have moved together, and scores how far each pair's price ratio has drifted from its recent normal. This guide explains both numbers, follows ETHUSDT / SOLUSDT from Diverged on 4 November 2026 to Converging on the next bar, and shows why one coin was the cheap leg in 7 of the 13 Diverged rows that day. The NSE version is in the Correlation & Pairs guide.
What correlation and a pair's z-score are
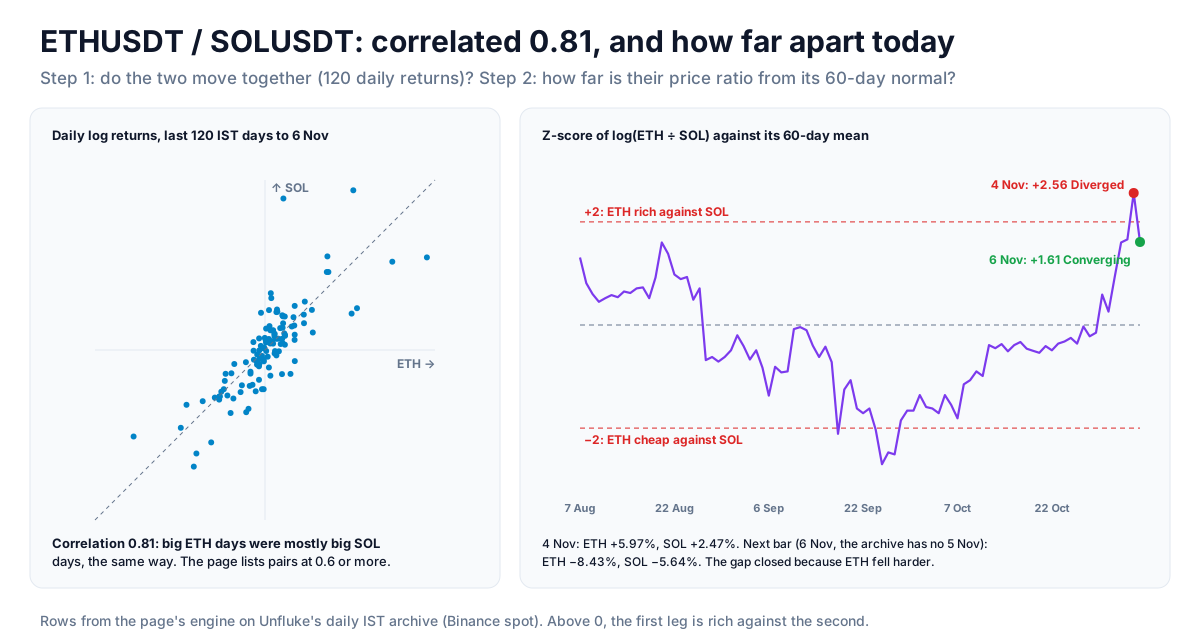
Correlation: do they move together?
Correlation runs from −1 to +1. At +1 two series always move the same way by matching amounts; at 0 there is no link. The page measures it on daily log returns over the last 120 bars, about four months of IST days, and keeps pairs at 0.6 or more.
The z-score: how far apart are they now?
Two coins can move together day to day while one quietly outruns the other over weeks. The page tracks the price ratio A ÷ B (in log form) and compares today's value with its average over the last 60 bars, in standard deviations:
z = (today's log(A ÷ B) − its 60-bar mean) ÷ its 60-bar standard deviation
- z near 0: the ratio sits where it usually does.
- z of +2 or more: A is rich against B. −2 or less: A is cheap against B. Either one is Diverged.
- Converging: |z| was 2 or more on the previous bar and is smaller today.
Which pairs are tested on crypto
- Every liquid pair against every other, as one group. NSE pairs stocks within a sector; crypto has no sectors, so the Sector column reads "Crypto" on every row. The page's note says "the 40 busiest pairs", but with 34 live pairs and the volume rule, in practice it is every pair listed that day: 20 on 6 November, 24 on 4 November.
- Traded on every one of the last 121 days the archive holds, so both price series line up bar for bar. A day missing for every pair (5 November 2026) is simply skipped.
- The Correlation Matrix (the button on the page) shows the 20 busiest liquid pairs against each other on 60 or 120 bars.
Which pairs are listed, and why the list changes size
- The live USDT pairs in Unfluke's crypto archive: 34 in November 2026. A pair is live if its feed has a bar within the last three days.
- Liquid today: a 20-day average turnover above US$500,000, and the day's volume above 0.8× its own 20-day average. Pairs whose average daily range is under 0.25% (the stablecoins, almost always) are left out.
The second rule matters more on crypto than on NSE. Crypto volume drops sharply at weekends, so on a quiet day most pairs trade under 0.8× their average and drop off every list. From 1 September to 7 November 2026 the pages listed a median of 17 pairs a day: about 19 on weekdays, about 10 on Saturdays and Sundays, as few as 1 (Saturday 7 November) and as many as 32 (Friday 30 October, a sell-off). A short list on a Sunday is the volume rule at work, not a broken page. For a fuller picture, read a weekday.
Reading the real rows: 4 and 6 November 2026
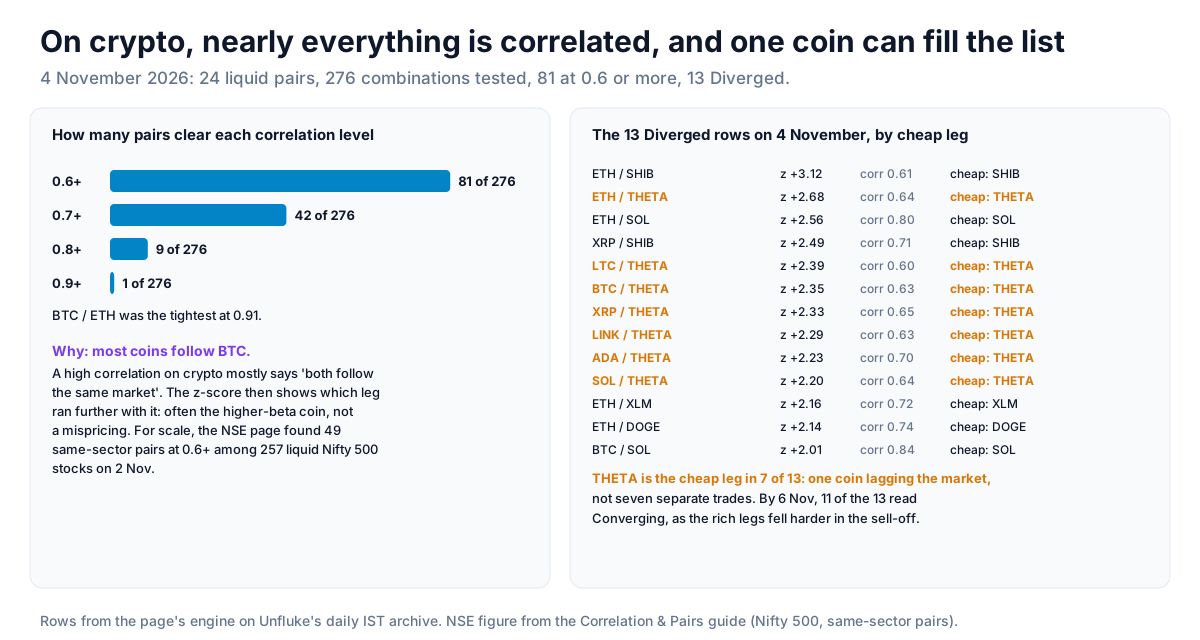
On 4 November 2026, 24 pairs passed the volume rule. That is 276 combinations; 81 had a correlation of 0.6 or more, 13 were Diverged and 4 Converging. The tightest pair was BTCUSDT / ETHUSDT at 0.91.
ETHUSDT / SOLUSDT: Diverged, then Converging
- 4 November: correlation 0.80, z +2.56 (from +1.66 the bar before): Diverged, ETH rich against SOL. ETH closed at 2,433.12, up 5.97%; SOL at 95.82, up 2.47%. The ratio was 25.39.
- 6 November (the next bar; the archive has no 5 November): correlation 0.81, z +1.61, down from +2.56: Converging. ETH fell 8.43% to 2,228.05, SOL 5.64% to 90.42. The ratio was 24.64.
The gap closed, but look at how: both fell, and ETH fell harder. On a rally day ETH ran further than SOL; on the sell-off it fell further. That is a difference in how strongly each one responds to the market (its beta), and it can open and close the gap again and again without either coin being mispriced.
One coin, seven rows
Of the 13 Diverged rows on 4 November, seven had THETAUSDT as the cheap leg: ETH, BTC, LTC, XRP, LINK, ADA and SOL were all at +2.2 to +2.7 against it. Over the previous weeks THETA had fallen behind the rest of the market. That is one coin lagging, not seven trading ideas. On 6 November, 11 of the 13 Diverged pairs had become Converging, including all seven THETA rows, as the rich legs fell harder in the sell-off.
On 6 November
With 20 liquid pairs, 52 were correlated at 0.6 or more, none were Diverged and 11 were Converging. A list that empties as fast as it filled is a sign that the divergences were the market's move, not the pairs'.
How to use it in a trade
Why nearly everything is correlated
On 4 November, 42 of the 276 crypto pairs were correlated at 0.7 or more. On NSE, the same page found 49 same-sector pairs at 0.6 or more among 257 liquid Nifty 500 stocks on 2 November, and only 11 at 0.7. Crypto pairs are so correlated because most coins follow Bitcoin. A high correlation here mostly says "both follow the same market", and a big z-score often says which coin moved further with it.
A step-by-step way to read the list
- Look at BTC first. If BTC moved hard that day, many pairs diverge at once. Expect them to compress again when BTC moves the other way, as they did on 6 November.
- Group the rows by coin. If one symbol appears in many Diverged rows, the story is that coin, not the pairs. Check its own news and volume (the Volume Shockers page).
- Prefer the strongest correlations. A z-score of 2.5 on a pair correlated at 0.85 is a cleaner read than 3.1 at 0.61 (ETH / SHIB on 4 November).
- Read Converging as information, not a signal. It says the gap shrank today. It does not say why: the rich leg may have fallen with the market.
- Check that both legs can be traded. A pair trade needs a short on one side. Use the Futures universe to see pairs that both have perpetual futures, and check funding before holding a short.
Risk per trade - risk a small, fixed share of capital on any one idea. Crypto never closes, so a stop is the only exit while you sleep; with leverage, keep the liquidation price well beyond the stop. When selling options, prefer defined-risk structures (spreads, iron condors) over naked positions.
Strategy ideas (ideas, not promises)
These are ideas to study, paper-trade and backtest, not recommendations or signals, and not a promise of any result. Every condition below can fail. Crypto trades around the clock and can move sharply at any hour; leverage and options can lose more than you expect, and past behaviour says nothing certain about the next session. Size, entries, exits and risk are your own decisions.
1. Beta-matched spread
- Setup: a pair correlated at 0.8 or more with |z| of 2 or more, both legs with perpetual futures.
- Idea: short the rich leg and buy the cheap one, sized so each leg carries the same daily volatility rather than the same dollar amount. That takes out most of the "one coin moves more" effect.
- Exit and invalidation: z back near 0 to take it off; z beyond 3, or correlation dropping under 0.6, to stop.
2. The lagging coin
- Setup: one coin is the cheap leg in many Diverged rows (THETA on 4 November).
- Idea: study it as a single-coin question: is it lagging for a reason (an unlock, a delisting, news), or simply slower? The pair rows tell you it is out of step, not which way it will resolve.
3. Correlation breaks
- Setup: in the Correlation Matrix, a pair whose 60-bar correlation is far below its 120-bar one.
- Idea: a recent break in a long relationship often comes from news about one coin. Treat it as a reason to research the coin, not as a trade.
Test before you trade - write the rules down exactly, test them on past data (see how to backtest an options strategy and the Option Simulator, which supports crypto), then paper-trade at least 20 occurrences before committing real money. Keep a journal of every trade, including the ones you skipped.
Every tab, filter and column
The tabs
- Diverged - |z| of 2 or more, largest first.
- Converging - |z| was 2 or more on the previous bar and is smaller today.
- All Pairs - every pair correlated at 0.6 or more, highest correlation first.
The filters
- Date - the newest IST day by default; signed-in users can pick an earlier one.
- Universe - All, Futures or Options.
The columns
- Pair - Leg A / Leg B.
- Leg A, Leg B - each coin's close and the day's change.
- Sector - always "Crypto".
- Corr - correlation of daily log returns over 120 bars.
- Z-score, Z Prev - today's and the previous bar's z of log(A ÷ B) against its 60-bar mean. Above 0, A is rich.
- Stretched - which leg is rich and which cheap.
- Signal - Diverged, Converging.
- Charts - each leg's daily candles.
The count under the tabs reads "N pairs from M pairs": M is the number of coins tested that day, not the number of combinations.
What the numbers are built from, and what they cannot tell you
- Correlation is not a link. Two coins that both follow BTC will correlate whether or not they have anything else in common. A pair can stay stretched, or stretch further, for a long time.
- Price ratios, not hedge ratios. The z-score is on the plain ratio A ÷ B, not a beta-weighted spread. When one coin is more volatile than the other, the ratio drifts with the market.
- Stablecoins. On a day a stablecoin passes the range rule (USDCUSDT did on 6 November) it is tested too; it correlates with nothing, so it adds no rows, but it can appear in the matrix.
- One exchange, spot only. The daily bars are rolled up from Unfluke's one-minute Binance spot archive into IST days, 00:00 to 23:59. Perpetual futures volume is not counted.
- Bars, not trading days. Every lookback counts daily bars, and crypto has a bar every day of the week. A "52-week" high is the highest of the last 252 bars, which is about eight months on crypto, not a year; a 200-day average spans about six and a half months.
- Missing days. The archive has no bar for 5 August, 11 September or 5 November 2026. On those dates the pages have nothing to show, and the next day's change is measured from the day before the gap, so it covers two days.
- The newest day can be unfinished. The daily bars are topped up during the day. Until 23:59 IST the day's volume is partial, so fewer pairs pass the 0.8× volume rule in the morning than at night. Signed-in users can pick a finished date.
- End of day only. Nothing here updates within the day from live prices; the scans are recomputed from the daily bars.
Where to go next
For strength against BTC, read the Relative Strength Rating guide; for the trend behind each leg, the Trend Template & Stages guide; for positioning in the perpetuals, the Perp Basis guide and the Binance Futures guide. The NSE version is explained in the Correlation & Pairs guide. Open the page at Watch List → Correlation & Pairs (switch the market to Crypto), or sign up free to open the Market Terminal.
More from the blog
- Strategy Backtesting on Unfluke
Backtest trading strategies on real Indian market data with Unfluke. Test equity, Nifty, Bank Nifty and options strategies with realistic costs and key metrics.
- Live Market Scanners
Explore Unfluke's real-time stock scanner for NSE markets. Scan 1,800+ stocks with 40+ technical indicators, fundamental filters, F&O data and custom rules.
- Option Strategy Simulator
Build and simulate multi-leg options strategies with Unfluke. Visualize payoffs, Greeks, max profit and loss, and replay historical option data from 2023.